Debt consolidation alternatives: what worked for Debbie and Alan
1 Sep 2026 |
Cheryl Hayford
|
If a debt consolidation loan has been declined, or taking on more debt does not feel like the right move, you still have options. Alternatives to debt consolidation can include a structured personal budget, creditor hardship support and negotiated repayment arrangements that help make existing debts more manageable without borrowing more money.
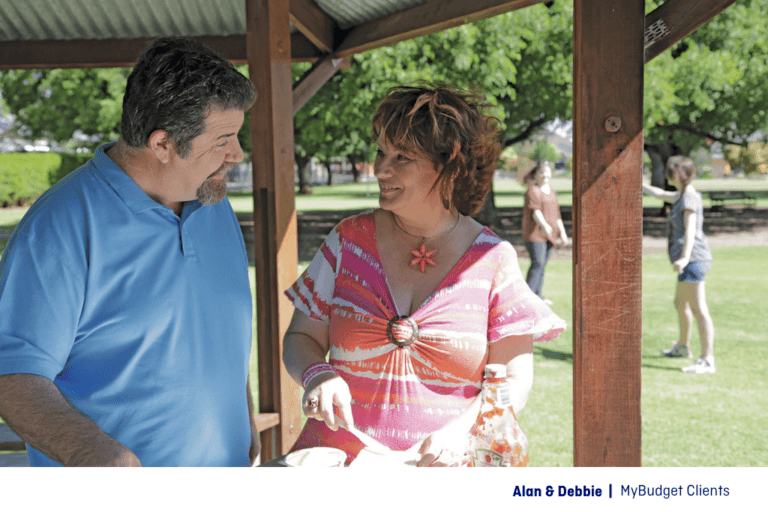
That was the situation for Debbie and Alan. Overwhelmed by personal debt and rejected for a consolidation loan, they worked with MyBudget to create a realistic repayment plan, manage their bills and negotiate with creditors. The result was a path forward that did not rely on another loan.
What is a debt consolidation loan?
Debt consolidation rolls multiple debts into a single new loan, usually with one interest rate and one repayment. For a full explanation of how it works, when it makes sense and what to watch out for, read our guide: Debt consolidation: is it right for you?
Why so many Australians are looking at debt consolidation alternatives
Finder reports average balances of $14,704 for personal loans, $3,193 for credit cards and $633 for buy now, pay later debt in June 2025, excluding home and investment loans. For Australians managing more than one type of personal debt, those repayments can quickly add pressure to an already stretched budget. Finder, 2025
With interest charges and living costs putting pressure on household budgets, it is easy to see why consolidation looks attractive. But for many Australians, taking out another loan may not be the right fit. Alternatives to debt consolidation can help make existing debts more manageable without adding another loan.
Debbie and Alan’s story: how MyBudget helped them tackle debt consolidation without a loan
Debbie and Alan, like many Australians, found themselves in financial uncertainty. Multiple credit cards, personal loans, and mounting weekly repayments were leaving them financially and emotionally drained. They needed an easy solution to manage and get out of their debt.
They thought a debt consolidation loan was the way out, but when the bank shut them down for not meeting the lending criteria, reality hit hard.
We were scared to answer the phone. We knew it was just another creditor chasing money we didn’t have. Alan | MyBudget client
At that point, Debbie and Alan owed money to multiple lenders: credit cards, a personal loan and an overdue car repayment. Each debt had its own due date, its own interest rate and its own penalty structure. Keeping track of what was owed to whom, and when, had become a job in itself.
When the bank rejected their consolidation application, it felt like the last door closing. They’d assumed consolidation was the answer, and without it, they didn’t know what was left to try.
That’s when they looked into a Part 9 Debt Agreement, which could have frozen creditor action and reduced what they owed. But the trade-off was steep: a five-year mark on their credit report, and restrictions on future borrowing. For a couple still hoping to get back on solid ground rather than start over, it was too heavy a price.
That’s when they turned to MyBudget, as a way to get out of debt, and everything changed.
Watch how Debbie and Alan found an alternative to debt consolidation
Debbie and Alan share how a structured budget helped them regain control of their debts without taking out another loan.
No Need For Debt Consolidation | Tackle Debt and Build Savings with Personal Budgeting - YouTube
No Need For Debt Consolidation | Tackle Debt and Build Savings with Personal Budgeting MyBudget
4 Alternatives to debt consolidation loans (that aren’t more debt rolled into one)
If you’re struggling with high-interest debt, you might think a debt consolidation loan is your only option. But here’s the truth, not everyone qualifies, and in some cases, it might not even be the best solution. The good news? There are other ways to take control of your current debt that could be a better fit for your individual circumstances rather than consolidation which is just rolling all your debts into another loan.
Here are four realistic alternatives to debt consolidation loans that could help you manage repayments, reduce financial pressure and regain control:
1\. MyBudget’s tailored personal budget and debt management plans
A consolidation loan restructures your debt. A personal budget restructures how your money moves, which is usually where the real problem sits.
Here’s what it might look like. Say your household brings in $1,200 a week after tax. Right now, your rent, groceries, utilities, transport and insurance take $850. That leaves $350 for debt repayments, savings and everything else. If your minimum repayments across four debts total $400, you’re short $50 every week. That gap is what pushes people toward credit cards and BNPL just to get through.
A consolidation loan might lower that $400 to $320 by stretching the term or cutting the rate. But a structured budget goes further. It maps every dollar of your $1,200 to a purpose. Your fixed costs, debt repayments ranked by priority, a small savings buffer and a realistic amount for day-to-day spending. Instead of money disappearing into whichever bill you receive first, everything is scheduled and accounted for across the next 12 months.
At MyBudget, your Money Coach builds this plan around your actual income, actual bills and actual debts. They also handle creditor negotiations on your behalf. This could mean arranging reduced repayments, pausing interest where possible and stopping collection calls. The budget isn’t a spreadsheet you fill in once and forget. It’s a managed plan with ongoing support, and your Money Coach adjusts it as your situation changes.
| How is a budget different from a consolidation loan? A consolidation loan simplifies your debt, but it doesn’t change the cashflow pressure that caused the debt to build up. A structured budget does both. It reduces the pressure and gives every dollar a job, so the gap that was growing each week starts to close. |
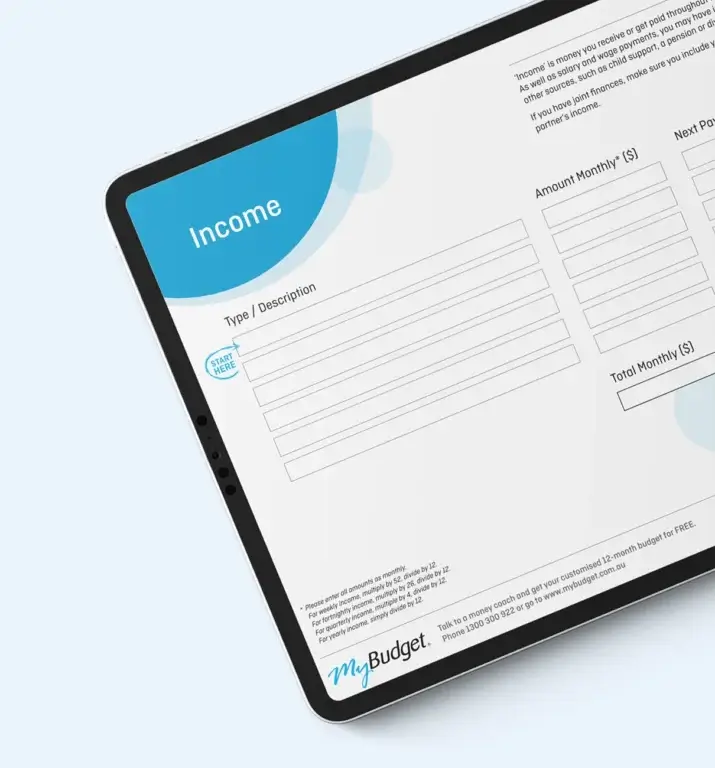
See how MyBudget’s debt management strategies can help organise repayments, negotiate with creditors and manage scheduled payments, or download our free Personal Budget Template to start mapping your numbers.
2\. How to negotiate with creditors yourself to reduce your outstanding debts without a consolidation loan
If you prefer to handle negotiations on your own as an alternative to a debt consolidation loan, you can contact your credit providers directly to request assistance. Many lenders are open to working with you if you take the initiative.
According to MoneySmart, banks and credit card companies are required by law to consider your request if you are experiencing financial hardship and want to avoid the debt consolidation path. They might waive late fees, lower the interest rate, or even freeze payments until you get back on your feet.
Before you pick up the phone, it helps to know what you’re walking into.
- What to prepare: Gather your account numbers, a summary of your income and expenses, and a realistic figure you can afford to repay. Creditors respond better when you can show you’ve done the maths and know what you can commit to.
- What the creditor will likely ask: Expect questions about your employment, household income, other debts and why you’ve fallen behind. They’re assessing whether you qualify for their hardship program, so be honest. Understating your situation to save face can mean you’re offered a plan you still can’t afford.
- What outcomes are realistic: Hardship arrangements vary by lender, but common outcomes include reduced repayments for a set period, a temporary freeze on interest, waived late fees, or an extended loan term. Full debt write-offs are rare at this stage. The goal is a repayment you can meet every week or fortnight without falling behind on essentials.
To make it easier, here are a few simple scripts to get the conversation started:
Ask for a lower interest rate
“Hi! I’m having difficulty keeping up with my outstanding credit card debt. Is there any chance you could lower my interest rate to help me out? It’d really make a difference in getting my finances back on track.”
Payment plan or hardship help
“Hello! I’m currently in a bit of financial stress and struggling to make my debt repayments. Could we set up a more manageable payment plan or discuss any debt relief options you might have?”
Waiving late fees
“Hi there! I’ve hit a bit of a rough patch with all these rate hikes and missed a payment. Any chance you could waive the late fee? I’m working hard to get a bit of extra cash to get my finances back in order.”
These scripts give you a starting point, but don’t feel locked into the wording. What matters is that you call, explain your situation clearly, and ask what options are available.
If the process feels overwhelming, or if your creditor pushes back, you don’t have to handle it alone. MyBudget’s Money Coaches negotiate with creditors on your behalf as part of every budgeting plan, and they do it every day. For more detail on how the process works, read our full guide on how to negotiate with creditors.
3\. Debt settlement
Some credit providers will accept a lump sum payment that’s less than the full balance you owe. This is sometimes called a “settlement offer” or “offer of compromise.”
Settlement can work if you have access to savings, a tax refund, or help from family. And your creditor agrees the reduced amount is better than the risk of receiving nothing. It’s most common with unsecured debts like credit cards and personal loans.
There are risks you need to be aware of. Not all creditors will agree, and a settled debt may still appear on your credit report as “settled for less than the full amount,” which can affect future borrowing. It’s worth getting advice before making an offer. A MyBudget Money Coach or a financial counsellor can help you understand whether settlement is realistic for your situation.
4\. Part 9 Debt Agreement
A Part 9 debt agreement is a formal, legally binding arrangement between you and your creditors under the Bankruptcy Act 1966. It lets you repay a reduced amount over an agreed period, and once it’s in place, creditors can’t continue chasing you for the debts covered by the agreement.
It’s a serious step. A Part 9 debt agreement can affect your ability to obtain credit. It may appear on your credit report for up to five years, or longer in some circumstances, and it is recorded on the National Personal Insolvency Index for a period that depends on how the agreement ends. You also need to meet eligibility requirements, such as your unsecured debts and assets being below set thresholds.
For some people, a Part 9 agreement is the right option when other alternatives aren’t suitable. But it’s not something to enter without advice.
Each option works differently, and the right one depends on your income, your debts and how much pressure you’re under. A MyBudget Money Coach can talk you through your options and help you decide.
27.8% of surveyed MyBudget clients paid off and cancelled their credit cards
Source: MyBudget 2026 Financial Wellbeing Report, client survey of 741 respondents.
Real life example: how MyBudget changed Debbie and Alan’s future
The alternative to a debt consolidation loan
After reaching out to MyBudget, Debbie and Alan sat down with a Money Coach who went through every dollar. Income, bills, debts, groceries, fuel, school costs, everything. For the first time, they could see the full picture in one place. Not just what they owed, but where their money was going each week and where the gaps were.
Their Money Coach built a 12-month plan that covered essentials first, then structured debt repayments around what they could realistically afford rather than what the lenders were demanding. Some weeks that meant smaller payments than the original minimums, negotiated directly with their creditors by MyBudget on their behalf.
One of the biggest reliefs?
That creditor negotiation was the part Debbie hadn’t expected. She and Alan had spent months fielding calls from collection teams, feeling the weight of it every time the phone rang. Once MyBudget stepped in, those calls stopped. MyBudget contacted each creditor, explained the situation, and arranged repayment schedules the household could actually sustain. With a personal budgeting plan, they had a repayment approach designed around what their household could realistically afford, without taking out another loan.
With their new budget, rather than a debt consolidation loan, they were able to:
- Cover their essential expenses without falling behind
- Set up automatic monthly repayments to avoid late fees
- Build better financial habits to set them up for long-term financial success
- Start building a savings buffer for financial emergencies.
Now, they’re no longer just surviving, they’re thriving with no need to have used a debt consolidation loan for their debts.
For the first time in years, we feel in control of our finances, we’re not just paying off debt, we’re planning for our financial future. Debbie | MyBudget client
What made the difference wasn’t a new loan or a single lump-sum fix. It was having someone map out a realistic plan, negotiate with the creditors they’d been avoiding, and keep the whole thing on track week to week. Debbie and Alan didn’t need to consolidate their debts. They just needed a system that made their existing income work better.
95% of surveyed clients who previously missed credit card repayments reported none since joining MyBudget
Source: MyBudget 2026 Financial Wellbeing Report, client survey of 741 respondents.
Who can help with debt consolidation when you need more support?
If you’re looking for free, independent guidance, the National Debt Helpline offers support from qualified financial counsellors.
If you want a more comprehensive, hands-on service, MyBudget offers a free appointment to help you explore your options and create a personalised plan based on your income, expenses, debts and goals. Unlike a DIY budgeting app that mainly helps you track your money, MyBudget combines smart budgeting technology and automation with ongoing support from real people. You can see your finances up to 12 months ahead, while our team helps manage the day-to-day budgeting and payments.
MyBudget stays by your side as you work towards paying off debt, building savings and achieving your financial goals. It is an all-in-one service designed not only to help you get out of debt, but to create the plan, habits and systems that can help you stay out of debt.
Debbie and Alan’s experience shows what that support can look like in practice: a solution tailored to their circumstances, a clear path forward and measurable progress towards a life free from money worries.
Ready to get out of debt without a consolidation loan?
A free budgeting appointment can help you understand your options and see how a personalised MyBudget plan could work for you.
With MyBudget, you can get:
- A personalised budget and debt repayment plan
- Help communicating and negotiating with creditors
- Bills and repayments managed through one structured system
- A 12-month view of your finances in the MyBudget app
- Ongoing human support as you pay down debt and build savings
Explore debt consolidation without a loan
Or call 1300 300 922 to discuss your situation with our team.
Still weighing up your options? Explore MyBudget’s Debt Consolidation Solutions to understand how consolidation works and when alternatives to debt consolidation may be worth considering.
Important information
This page provides general information only. It does not take your personal circumstances into account and is not personal financial advice. For the scope and licensing of a particular service, check the service provider's current disclosures or contact MyBudget.
What is the article 'Alternatives to Debt Consolidation: Your Options' about?
It's a MyBudget Money Hub success story article that explores practical debt management solutions beyond traditional consolidation loans, aimed at people whose debt consolidation loan has been declined or who don't want to take on more debt. It documents how MyBudget clients Debbie and Alan got debt-free using these alternatives.
Who wrote the article on debt consolidation alternatives?
The article was written by Cheryl Hayford.
What is a tailored personal budget and debt management plan as an alternative to consolidation?
Rather than restructuring debt through a new loan, a structured personal budget restructures how your money moves. A MyBudget Money Coach creates a comprehensive plan that maps every dollar of income to a specific purpose, prioritizes debt repayments strategically, includes a small savings buffer, allocates realistic amounts for day-to-day spending, and handles creditor negotiations on your behalf to arrange reduced repayments and pause interest where possible.
What is creditor negotiation and hardship support?
According to MoneySmart, banks and credit card companies are legally required to consider requests from individuals experiencing financial hardship. Potential outcomes of such requests include reduced repayments for a set period, temporary interest freezes, waived late fees, and extended loan terms.
What is debt settlement as an alternative to debt consolidation?
Debt settlement is when some credit providers accept a lump-sum payment that is less than the full balance owed. This approach works best when you have access to savings or family assistance, and it works most commonly with unsecured debts like credit cards and personal loans.
What is a Part 9 Debt Agreement?
A Part 9 Debt Agreement is a formal, legally binding arrangement under the Bankruptcy Act 1966 that allows repayment of a reduced amount over an agreed period. It is described as a serious step, implying it should be considered carefully compared to other alternatives.
Who are Debbie and Alan in the context of this article?
Debbie and Alan are MyBudget clients whose success story is featured in the article as an example of people who got debt-free by exploring debt consolidation alternatives that worked without more borrowing.
Why would someone look for alternatives to debt consolidation?
Someone might look for alternatives if a debt consolidation loan has been declined, or if taking on more debt doesn't feel like the right move for them, yet they still want options to make existing debts more manageable without borrowing.
Images on This Page
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/customer-support.png
Call Desk Profile Picture
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/1-mybudget-app-budgeting-australia-flexibility-2.webp
The MyBudget app demonstrating flexible budget planning and debt management features for Australians to reach financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/adam-erin-couple-client-stories-mybudget-australia.webp
MyBudget clients Adam and Erin, a couple, featured in client stories celebrating achieved financial goals and budget planning success in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/tammy-tips.png
Tammy Barton, Founder and Director of MyBudget, giving her financial tips.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/megan-creagh-client-stories-mybudget-australia-e1764824164539.webp
MyBudget clients Megan and Creagh featured in client stories celebrating achieved financial goals and successful debt solutions in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/tammy-podcast-intro.png
Tammy Barton, Founder and Director of MyBudget, introducing a podcast on budgeting help and achieving financial goals for Australians.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/Michelle-phil-mybudget-clients-australia-transparent-e1765848811345.png
A happy couple, Michelle and Phil, clients of MyBudget Australia, are captured mid-high-five, celebrating their financial success and effective budgeting. The man looks surprised and excited, while the woman is smiling broadly, highlighting the positive results of using MyBudget services to achieve their financial goals in Australia. This image represents the satisfaction and relief of managing personal finances effectively.
-
https://www.mybudget.com.au/wp-content/uploads/2025/02/debbie-and-alan-mybudget-clients-australia-768x512.png
MyBudget clients Alan and Debbie enjoying time together after taking control of their finances with MyBudget.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/alyssa-pete-family-budget-clients-mybudget-australia.webp
MyBudget clients Alyssa and Pete and family using effective budget planning to achieve financial goals and overcome debt solutions in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/aaron-jake-mybudget-australia-clients-pay-off-credit-card-debt-1-1-768x512.webp
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/04/megan-and-creagh-paid-off-debt-faster-with-mybudget-scaled-1-768x512.jpg
MyBudget clients, Megan & Creagh found debt solutions that helped them get back on track and start saving.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/budget-template-personal-resource-mybudget-austalia-715x768.webp
Tablet displaying MyBudget’s Personal Budget Template for Australian users, to help organise finances, get out of debt, start saving and reach financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/call-to-action-image.jpg
Call-to-action image encouraging Australians to seek MyBudget for expert debt solutions and financial coaching.
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/mybudget-trustpilot-australia.webp
Trust Pilot
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/ProductReview-mybudget-reviews-white.png
Product Review
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/Google-mybudget-reviews-white.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/mybudget-app-store.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/my-budget-google-play.png
(no alt text)
-
https://bat.bing.com/action/0?ti=17543562&tm=gtm002&Ver=2&mid=f0e4ab80-d50b-43d5-9ca2-ecf1d0a5f01c&bo=1&sid=706d78e0b0a411f19af0473c1a1081a1&vid=706dc900b0a411f1a7389f2b4e5716e9&vids=1&msclkid=N&pi=918639831&lg=en-US&sw=800&sh=600&sc=24&nwd=1&tl=Alternatives%20to%20Debt%20Consolidation%3A%20Your%20Options%20%7C%20MyBudget&p=https%3A%2F%2Fwww.mybudget.com.au%2Fmoneyhub%2Farticles%2Fsuccess-stories%2Falternatives-to-debt-consolidation%2F&r=<=9697&evt=pageLoad&sv=2&cdb=AQAQ&rn=299460
(no alt text)