The cost of financial avoidance: when doing nothing costs more than money
Published on 15 Oct 2026 | By Tammy Barton | 8 min read.
One of the most damaging assumptions people bring to a money conversation is that needing help means they have failed. Before the facts are even on the table, a late bill or missed payment has often become a judgement about their character.
But your bank balance is information, not a verdict.
Over more than 25 years, I have seen financial avoidance show up most often when life is already demanding too much. Work, family, appointments and everyday admin can fill every bit of attention you have. Putting off one more decision can feel like relief. Unfortunately, the charges and due dates keep moving while you catch your breath.
Financial avoidance is putting off looking at, talking about or acting on your money because it feels overwhelming. It can start with one unopened email and quietly grow into late fees, extra interest, lost time, financial stress and fewer choices. What helps is not another lecture. It is one clear next move and a plan that works in real life.
If your budget has no place for a bill, your mental load carries it instead.
Tammy Barton | MyBudget Founder & Director
Why do capable people avoid dealing with money?
Capable people can still put money off when the admin has become one demand too many. If each payment seems urgent and the numbers feel tight, delaying the decision may be how you get through a busy day. That response is understandable, but it does not stop the cost from growing.
Willpower can get you started, but it is a poor filing cabinet for due dates. A household budget should hold the dates and priorities for you, so you do not have to rebuild the plan in your head every payday.
Financial avoidance can give you relief today, but it sends the cost to your future self.
Tammy Barton | MyBudget Founder & Director
What is financial avoidance really costing you?
Financial avoidance can cost you in money, time, sleep, relationships and missed opportunities. The first costs may look small, but late fees, overdraft charges and interest can build while the worry uses energy you need elsewhere.
- Late fees, overdue charges, avoidable interest and greater reliance on credit
- Hours spent moving money, juggling accounts and fixing missed dates
- Savings, debt repayments and future opportunities repeatedly postponed
- Financial stress that drains sleep, concentration and patience at home.
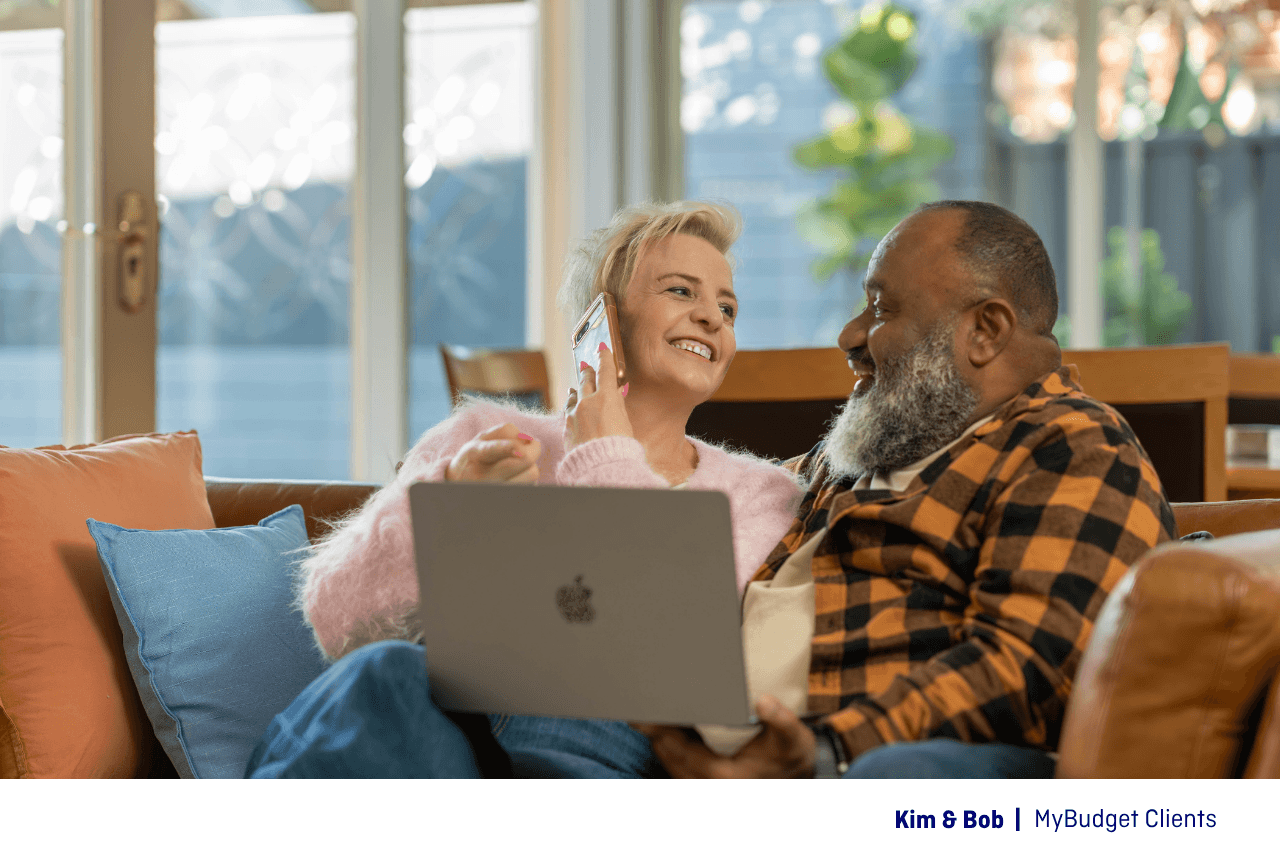
MyBudget clients Kim and Bob compared the cost of getting help with what their existing cycle was already costing them. When Kim reviewed a full year of overdue fees, late fees and interest, she found those charges were higher than the MyBudget fee.
Kim put it simply: “We were actually saving money by joining MyBudget.” You can read their inspiring client story.
97% of clients bills were paid on time after joining MyBudget
The fair question is not only, “What would financial support cost?” It is also, “What is staying stuck already costing me?”
How can financial stress affect wellbeing and relationships?
Financial pressure rarely stays confined to your bank accounts. It can interrupt sleep, drain concentration and shorten your patience with the people closest to you. A routine question about a bill can suddenly feel like an accusation when everyone is already worried.
In many households, one person can become the default money manager. They remember the direct debits, upcoming costs and dates nobody else sees. Unless that responsibility and mental load is made visible, the workload and worry can build on one side of the relationship.
Please do not confuse being overwhelmed with being incapable. A shared view can reduce blame and make the next conversation more practical. This guide to talking about money in a relationship can help you begin.
93% of clients reported feeling significantly less stressed
Why does bill shock keep happening?
Bill shock often happens because non-monthly expenses are left outside the plan until they arrive. Rego, insurance, school costs, repairs, birthdays, Christmas and medical appointments do not happen every fortnight, but they are still part of real life.
When an annual bill disrupts the month, it is easy to think you should have managed better. Usually, the budget stopped at the next pay cycle. You may be managing a 12-month life through a two-week window. Irregular does not always mean unknowable.
When you are living pay to pay, even a known bill can feel like a shock. A forward-looking household budget turns one large future cost into smaller amounts across the pays before it. The bill may still be unwelcome, but it no longer has to be solved in a single payday. These ideas for moving beyond living pay to pay can help you begin.
What changes when you stop reacting and start planning?
Planning lets you prepare for upcoming expenses before they become urgent. It reduces the number of times you have to rethink the same problem, makes priorities clearer and helps you respond with more confidence when something changes.
Choose one manageable action and begin there:
- Choose one bill or account you have been avoiding. Record the balance, due date and next action. Nothing more
- List three non-monthly expenses likely to arrive during the next 12 months
- Work out one small amount you could put aside from each pay towards the nearest expense
- Choose one place to get help if the numbers still feel too heavy to carry alone.
The first win might be paying one bill on time, setting aside a small buffer or having a calmer conversation at home. Each completed action gives you useful evidence that a different pattern is possible.

What does doing nothing cost compared with taking action?
Doing nothing can keep charging you in ways that are easy to miss, while a clear system can give back time, headspace and choice. The value of support should be considered alongside the financial and emotional cost of continuing as you are.
| What financial avoidance can cost | How a clear money system can help |
| Late fees, overdue charges and avoidable interest | Bills and repayments can be planned around their due dates |
| Hours spent juggling accounts and transfers | Fewer repeated decisions and less mental load |
| Tense or avoided money conversations | A shared view can support calmer conversations |
| Debt, savings and future goals repeatedly postponed | Regular allocations can move goals forward |
| Credit absorbing the next unexpected expense | A cash buffer can absorb the next unexpected expense |
We are a human-led managed budgeting service. It combines personalised 12-month cash-flow planning, bill management and Money Coach support while you remain in complete control of your money.
We do not publish one standard price because support is tailored. Your first appointment and personalised 12-month plan are free. If you join, the establishment and weekly administration fees appear in your proposed budget before you decide. See how much MyBudget costs and what is included to compare the service with what staying stuck may already be costing.
When is asking for financial help the strongest move?
Ask for help when money is regularly affecting essential payments, sleep, relationships or your ability to plan beyond the next payday. A second set of eyes can help you understand what needs attention first and which choices are actually available.
The right support depends on your situation. Free financial counselling may suit hardship or urgent debt. A DIY budget can work if you have the time to maintain it. Human-led budgeting support can help when you want both a forward plan and practical help carrying it through.
Good support should leave you with more understanding and more control. You are allowed to share the work. If you want to see what that support looks like in everyday life, explore Our client stories and reviews.
Key takeaway
Financial avoidance is rarely free. It can add late fees and interest, increase mental load, strain relationships and delay your choices. The first step is not a perfect budget. It is seeing what is happening and taking one realistic action.
Financial progress can be as ordinary as opening a bill without dread because you prepared for it. Choose one account, record the essential facts and decide the next move. If the task still feels too heavy, bring someone into the conversation.
What happened before can inform your next decision without controlling it. Start with the choice in front of you, and let that choice create another option.
Shame solves nothing. Clarity changes everything
Tammy Barton | MyBudget Founder & Director
Ready to see what doing something could look like?
Your first appointment and personalised 12-month budget plan are free. You can see what is possible, how any fees fit and whether MyBudget feels right for you before making a decision. Book your free appointment, or:
Financial Avoidance FAQs
Can’t find what you’re looking for?
See more FAQs…
Make the task smaller than the fear around it. Choose one account and record only three things: the balance, due date and next required action. Then decide whether you can act, need to contact the provider or want another person beside you. You are not trying to solve every part of your finances in one sitting; you are turning one unknown into information you can use.
Yes. A balance can continue to grow through interest, late fees, overdue charges or missed-payment costs even when you are not making new purchases. Avoiding the account can also mean missing a chance to ask the provider about hardship support or a manageable arrangement. Checking the current balance and charges gives you the information you need to decide what to do next.
Begin with the nearest known expense and divide it across the pays remaining before it is due. Even if you cannot save the full amount yet, setting aside something reduces the gap you will need to cover later. Then review timing, subscriptions and flexible spending to find room. A forward-looking household budget can help you prioritise several irregular bills without treating them all as emergencies.
Paid budgeting support may be worth considering when you understand the basics but need help building a realistic plan, organising bills and keeping the system running. Compare the full fee structure with the late fees, interest, time and financial stress your current situation may be creating. You should understand what is included, see how the fees fit your proposed budget and decide without pressure.
This article has been prepared for information purposes only, and does not constitute personal financial advice. The information has been prepared without taking into account your personal objectives, financial situation or needs. Before acting on any information in this article you should consider the appropriateness of the information having regard to your objectives, financial situation and needs.
Important information
This page provides general information only. It does not take your personal circumstances into account and is not personal financial advice. For the scope and licensing of a particular service, check the service provider's current disclosures or contact MyBudget.
Read the original MyBudget article.
Why do capable people avoid dealing with money?
Capable people can still put money off when the admin has become one demand too many. If each payment seems urgent and the numbers feel tight, delaying the decision may be how you get through a busy day. That response is understandable, but it does not stop the cost from growing. Willpower can get you started, but it is a poor filing cabinet for due dates.
What is financial avoidance really costing you?
Financial avoidance can cost you in money, time, sleep, relationships and missed opportunities. The first costs may look small, but late fees, overdraft charges and interest can build while the worry uses energy you need elsewhere. MyBudget clients Kim and Bob compared the cost of getting help with what their existing cycle was already costing them. When Kim reviewed a full year of overdue fees, late fees and interest, she found those charges were higher than the MyBudget fee.
How can financial stress affect wellbeing and relationships?
Financial pressure rarely stays confined to your bank accounts. It can interrupt sleep, drain concentration and shorten your patience with the people closest to you. A routine question about a bill can suddenly feel like an accusation when everyone is already worried. In many households, one person can become the default money manager. They remember the direct debits, upcoming costs and dates nobody else sees. Unless that responsibility and mental load is made visible, the workload and worry can build on one side of the relationship.
Why does bill shock keep happening?
Bill shock often happens because non-monthly expenses are left outside the plan until they arrive. Rego, insurance, school costs, repairs, birthdays, Christmas and medical appointments do not happen every fortnight, but they are still part of real life. When an annual bill disrupts the month, it is easy to think you should have managed better. Usually, the budget stopped at the next pay cycle. You may be managing a 12-month life through a two-week window. Irregular does not always mean unknowable.
What changes when you stop reacting and start planning?
Planning lets you prepare for upcoming expenses before they become urgent. It reduces the number of times you have to rethink the same problem, makes priorities clearer and helps you respond with more confidence when something changes. The first win might be paying one bill on time, setting aside a small buffer or having a calmer conversation at home. Each completed action gives you useful evidence that a different pattern is possible.
What does doing nothing cost compared with taking action?
Doing nothing can keep charging you in ways that are easy to miss, while a clear system can give back time, headspace and choice. The value of support should be considered alongside the financial and emotional cost of continuing as you are. We are a human-led managed budgeting service. It combines personalised 12-month cash-flow planning, bill management and Money Coach support while you remain in complete control of your money. We do not publish one standard price because support is tailored. Your first appointment and personalised 12-month plan are free.
When is asking for financial help the strongest move?
Ask for help when money is regularly affecting essential payments, sleep, relationships or your ability to plan beyond the next payday. A second set of eyes can help you understand what needs attention first and which choices are actually available. The right support depends on your situation. Free financial counselling may suit hardship or urgent debt. A DIY budget can work if you have the time to maintain it. Human-led budgeting support can help when you want both a forward plan and practical help carrying it through.
What is financial avoidance?
Financial avoidance is the habit of putting off dealing with money: leaving bills unopened, not checking balances, or deferring decisions because looking feels worse than not looking. It is common among otherwise capable people, and the article's argument is that the avoidance itself carries a cost, separate from whatever the underlying financial position turns out to be.
What are the warning signs of financial avoidance?
Common signs include leaving mail or emails from creditors unopened, avoiding checking account balances, feeling a spike of anxiety when money comes up in conversation, and repeatedly deferring a decision you know needs making. The pattern tends to reinforce itself, because the longer a situation goes unexamined the more daunting examining it becomes.
What is the first step out of financial avoidance?
The first step is usually to look at the actual position rather than the imagined one, because the imagined version is often worse. From there a forward plan replaces guesswork with something you can act on. A free, no-obligation MyBudget appointment is one way to do that with someone else carrying the administrative side.
Can MyBudget help if I have been avoiding my finances?
Yes. MyBudget's starting point is a free appointment in which we analyse your finances, explore your options and build a personalised twelve-month budget that is yours to keep. There is no pressure and no judgement. For people who have been avoiding the detail, having someone else do the analysis is often what makes the first step possible.
Is this article personal financial advice?
No. The page provides general information only. It does not take your personal circumstances into account and is not personal financial advice. For the scope and licensing of a particular service you should check that provider's current disclosures or contact MyBudget. Free, independent and confidential financial counselling is also available from the National Debt Helpline.
Images on This Page
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/customer-support.png
Call Desk Profile Picture
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/1-mybudget-app-budgeting-australia-flexibility-2.webp
The MyBudget app demonstrating flexible budget planning and debt management features for Australians to reach financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/adam-erin-couple-client-stories-mybudget-australia.webp
MyBudget clients Adam and Erin, a couple, featured in client stories celebrating achieved financial goals and budget planning success in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/tammy-tips.png
Tammy Barton, Founder and Director of MyBudget, giving her financial tips.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/megan-creagh-client-stories-mybudget-australia-e1764824164539.webp
MyBudget clients Megan and Creagh featured in client stories celebrating achieved financial goals and successful debt solutions in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/tammy-podcast-intro.png
Tammy Barton, Founder and Director of MyBudget, introducing a podcast on budgeting help and achieving financial goals for Australians.
-
https://www.mybudget.com.au/wp-content/uploads/2026/11/mybudget-mymoney-budgeting-book-tammy-barton-pre-order-scaled.webp
Close-up portrait of Tammy Barton wearing a bright turquoise button-up shirt, smiling with her chin resting lightly on her hand against a solid black background. In the foreground on the left is an angled hardcover copy of her book, MyBudget MyMoney: How to Live Your Life Free from Money Worries, with the header text:
-
https://www.mybudget.com.au/wp-content/uploads/2026/07/mybudget-clients-kim-bob-budget-planning-home-australia.png
null
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/personal-budget-template-cta-mybudget-australia.webp
CTA for Australians to download a MyBudget personal budget budget template for effective budget planning and financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/tammy-barton-mybudget-founder-and-director-december-checklist-start-the-new-year-strong-1.webp
Tammy Barton, Founder and Director of MyBudget Australia
-
https://www.mybudget.com.au/wp-content/uploads/2025/06/why-am-i-always-broke-mybudget-scaled-2-768x512.jpg
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/tammy-barton-mybudget-founder-and-director-positive-money-mindset-best-asset-1-768x528.webp
Tammy Barton, Founder and Director of MyBudget
-
https://www.mybudget.com.au/wp-content/uploads/2026/09/mybudget-financial-wellness-report-2026-client-survey-australia-768x768.webp
MyBudget team member Tiff with MyBudget client Kim at a desk looking at the MyBudget Financial Wellness Report 2026 on a laptop.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/call-to-action-image.jpg
Call-to-action image encouraging Australians to seek MyBudget for expert debt solutions and financial coaching.
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/mybudget-trustpilot-australia.webp
Trust Pilot
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/ProductReview-mybudget-reviews-white.png
Product Review
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/Google-mybudget-reviews-white.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/mybudget-app-store.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/my-budget-google-play.png
(no alt text)